More breathing room
$650,000
$4,191/moTotal cash$144,296
DTI18.29%
Within payment & cash ceilings
YOUR FIRST HOME · YOUR FINANCING PLAN
A clear plan. Room for your life.
MAKE THE NUMBERS YOURS
General planning uses 0.70% annual taxes, 0.65% annual insurance and $0 HOA.
Conventional seller-credit limit: 6% ($42,000) at 80.00% CLTV. Assumes appraised value is at least the price unless Jordan supplies an appraisal. Other interested-party credits count toward this limit.
Down payment stays at 20%. Rate changes estimate payments; choose a quoted rate below to see points and cash to close.
YOUR CURRENT WHAT-IF
$487 below your payment ceiling
Within your maximum cash goal
Earnest money is part of your total contribution, not an extra cost. Seller credits cover eligible costs, not the down payment. Jordan must confirm program limits and eligibility.
JORDAN’S STARTING OPTIONS
These starting options use general tax and insurance percentages and $0 HOA. The home comparisons below use each property’s listed taxes and confirmed dues.
More breathing room
Within payment & cash ceilings
A middle ground
Within payment & cash ceilings
Your $700,000 plan
Within payment & cash ceilings
PAY LESS EACH MONTH OR BRING LESS UPFRONT?
At $700,000, with $10,000 in planned seller credits. The 7.490% reference rate has no discount points and includes a small lender credit. Savings and break-even compare each option with that rate. The 7% starting scenario includes points. These are permanent rate options, not temporary buydowns.
| Rate | Points / credit | Full monthly payment | Total client cash | Savings vs. 7.490% | Rate-cost break-even* | |
|---|---|---|---|---|---|---|
| 6.375% | $28,146 | $4,281 | $173,073Over cash ceiling | $418 | 68 months | |
| 6.490% | $24,819 | $4,323 | $169,802Over cash ceiling | $376 | 67 months | |
| 6.500% | $23,268 | $4,327 | $168,255Over cash ceiling | $372 | 63 months | |
| 6.625% | $20,446 | $4,373 | $165,494Over cash ceiling | $326 | 64 months | |
| 6.750% | $17,685 | $4,420 | $162,793Over cash ceiling | $280 | 64 months | |
| 6.875% | $14,851 | $4,466 | $160,019Over cash ceiling | $233 | 65 months | |
| 6.990% | $12,197 | $4,509 | $157,421 | $190 | 66 months | |
| 7.000% | $10,556 | $4,513 | $155,785 | $186 | 58 months | |
| 7.125% | $8,008 | $4,560 | $153,297 | $139 | 59 months | |
| 7.250% | $4,654 | $4,608 | $150,003 | $92 | 53 months | |
| 7.375% | $2,285 | $4,655 | $147,694 | $44 | 56 months | |
| 7.490% | Credit $157 | $4,699 | $145,308 | Reference rate | — |
Pricing supplied October 7, 2026; subject to change and rate lock. Points scale with loan amount for planning; a different price requires updated lender pricing. *Additional net rate cost (discount points minus lender credit) compared with the reference rate, divided by monthly payment savings. Includes the lender credit you give up by choosing a lower rate; excludes time value of money, tax effects and loan-balance changes. APR is not calculated for what-ifs.
PUT SELLER CREDITS TO WORK
A credit toward closing costs keeps more money in your pocket today. A lower rate can reduce your payment each month, but often uses more cash upfront.
Less spent on points
Your starting rate
Lower monthly payment
¹A points-first allocation for illustration. Moving a fixed credit between eligible fees does not itself change payment or total cash; choosing a different rate and points cost does. Concessions must be negotiated and lender-approved; unused credit is not cash back.
POSSIBLE AND COMFORTABLE CAN BE DIFFERENT
We start with what feels comfortable for your life. DTI explains the loan math; it does not determine approval on its own.
DTI = (housing payment + monthly debts) ÷ qualifying gross income. Income must be verified by Jordan.
Based on the selected rate, seller credit, 20% down and current property assumptions. This is a comfort-budget estimate, not maximum approval. Jordan has not supplied an underwriting DTI ceiling.
THE HOMES YOU’RE CONSIDERING
Compare at your selected 7.000% rate, with 20% down and $10,000 in assumed seller credits. Seller credits are a negotiation scenario, not an offer from either seller.
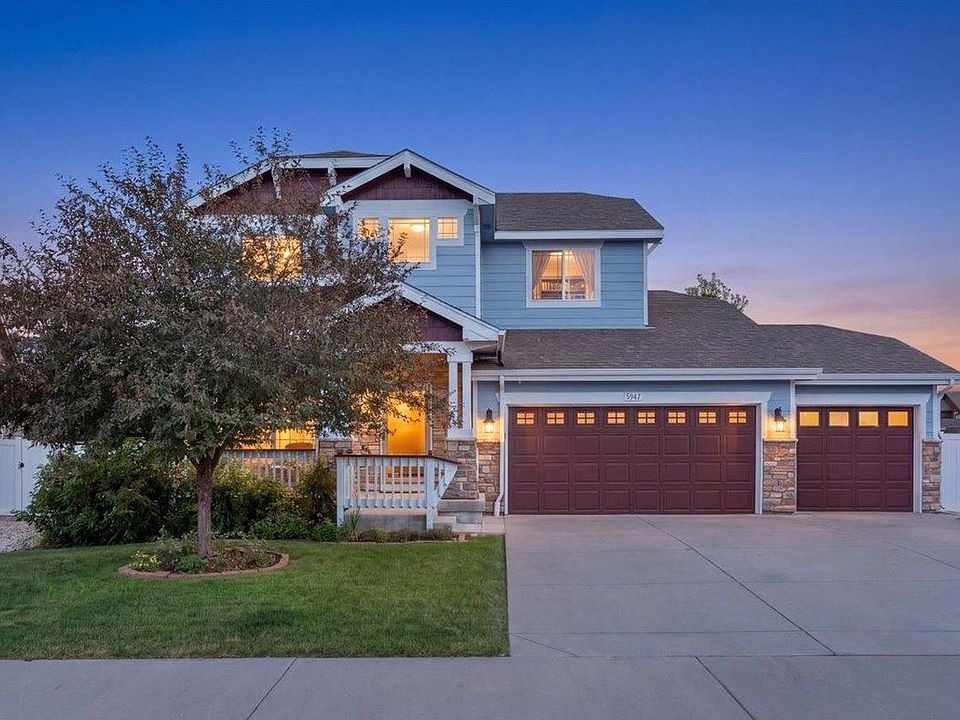 View on Zillow
Loveland, CO 80538
$615,000
4 beds · 3 full + 1 half baths · 4,109 total sq ft
Within your payment & cash ceilings
Listed August 18, 2026 · Details checked October 7, 2026
Main-floor primary suite, unfinished basement and three-car garage. Listed at $649,000; the listing records reductions to $625,000 on September 9 and $615,000 on October 2. Finished above-ground area is listed as 2,562 sq ft; confirm total and finished area with Feliz.
Source: Zillow listing. Historical taxes may change; Feliz and Jordan will confirm taxes, dues and fees before finalizing the plan.
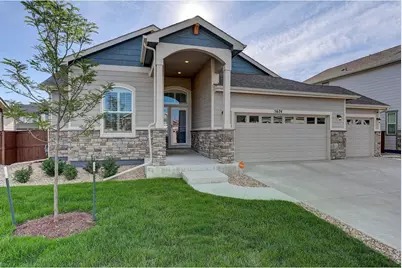 View on Zillow
Loveland, CO 80538
$675,000
4 beds · 3 full baths · 3,562 total sq ft
Within your payment & cash ceilings
Listed September 4, 2026 · Details checked October 7, 2026
Ranch layout, partially finished basement and three-car garage. Listing states 3,562 total sq ft and 3,259 sq ft of living area; confirm measurements with Feliz.
Source: Listing brokerage; no HOA confirmed by Jordan. Historical taxes may change; Feliz and Jordan will confirm taxes, dues and fees before finalizing the plan.
YOUR HOMEBUYING TEAM
YOUR MORTGAGE GUIDE
Owner | Mortgage Broker
Miller Mortgage
Questions about the payment, rate or cash needed? Let’s walk through your financing together.
YOUR REAL ESTATE GUIDE
REALTOR®
Berkshire Hathaway HomeServices Rocky Mountain, REALTORS®
Questions about the home, a showing or offer terms? Connect with Feliz to plan your next step.
970-672-6932 · CO 100085828
A NOTE FROM JORDAN
Your first home should leave room for the life you want to live in it. Let’s compare the monthly payment and the money you bring upfront, then choose a plan that feels right for both of you.
The email button opens a draft for you to review and send. Nothing is sent automatically.
WHAT FIRMS UP, AND WHEN
Final pricing depends on loan structure and when you lock. A slider value is not an available rate offer.
We use 0.70% and 0.65% of price annually. Actual property taxes and insurance quotes can change the payment.
Prepaids assume 31 days of interest, 12 months of insurance, and 3-month tax and insurance reserves. Closing date and escrow setup can change these amounts.